MODNAR Open the demo →
Lending operating system · for NBFCs

One line runs every loan.

Origination, underwriting, servicing, collections, co-lending and the books on one core. Forty-nine loan products come in. One ledger comes out.

49loan products
30apps, one sign-in
6stations on the line
1double-entry ledger
Why we built it

An Indian NBFC runs one loan through *six *systems that don't talk to each other, and reconciles them by hand at month end. MODNAR puts that loan on *one *line.

The problem

Lending teams don't have a system. They have six.

A CRM nobody likes, an LOS from one vendor, an LMS from another, a collections tool bought separately, and a finance team reconciling all of it in spreadsheets at month end. Six licence fees, six support queues, and no single view of a customer.

How it works today

  • Every new loan product means a change request to four vendors, four quotes and a six-week wait.
  • The same customer exists four times, with four different addresses.
  • Nobody can say what a bureau pull cost last month, because nobody logs the calls.
  • Collections works off a spreadsheet exported on Monday and already stale by Tuesday.
  • The ledger is reconstructed at month end rather than posted as it happens.
  • A complaint lives in an inbox, and the grievance officer finds out when the Ombudsman writes.

How MODNAR works

  • One customer record, one application, one loan, one ledger entry, from lead to closure.
  • A new product is configured in the console by your credit team and live on the next application.
  • Every bureau, KYC and payout call is logged against the application that triggered it.
  • Collections reads the same book the LMS writes, updated as repayments post.
  • Double-entry postings are written at the moment of the event, not rebuilt afterwards.
  • Support, marketing, payroll and procurement read the same book: an escalation lands in the grievance register, an incentive moves when a case cures.
The loan line

Follow one loan from a phone to the books.

Keep scrolling. On the right, the ledger posts each step as it happens: every rupee is a balanced journal entry, not a spreadsheet at month end.

01 / 06 · APPLY

Minutes,
not days.

The borrower applies on a phone: OTP and consent, dedupe, bureau pull, offers from every lender on the platform, KYC, bank check, key fact statement, e-sign and e-mandate. Branch, DSA and dealer channels sit on the same file.

Consent firstOffers from every lenderKFS & e-signe-mandate
02 / 06 · DECIDE

Every check.
One file.

A rules engine you configure yourself: gates, refer rules, segments, pricing bands and straight-through rules, versioned and dry-run before they publish. Underwriting can be manual, rule-driven, or assisted by a model you choose, always with a reason on the file.

Versioned rulesDry-run & rollbackMaker-checkerExplainable assist
03 / 06 · SANCTION & DISBURSE

Booked the moment
it's paid.

Sanction, fee deduction with GST, payout and booking happen as one step. The loan, its repayment schedule and its opening entries land in the loan book together, including branch cash disbursals.

Fees & GSTBroken-period interestBranch cash
04 / 06 · SERVICE

Re-planned
in seconds.

Credit Studio runs the repayment engine for every structure: EMI, bullet, interest-only, step-up, moratorium, part-payment, rate reset, tenure change. Each servicing change re-plans the schedule and posts its own entries.

Day-count rulesMoratoriumPart-pay & foreclose
05 / 06 · COLLECT

Day one.
Not day thirty.

A case opens on the first missed day. DPD buckets, promises to pay, field and agency allocation, dunning, settlement, write-off and legal all work from the same loan, so collections never chase a stale export.

DPD bucketsPromise to payAgenciesSettlement & legal
06 / 06 · CLOSE THE BOOKS

One ledger.
On time.

Daily accrual, month-end close, expected credit loss, GST and controls run on the same double-entry ledger, with reconciliation against payment gateways, banks and lender files. Finance, risk and compliance read one book.

Accrual & EOMECL stagingReconciliationPeriod lock
The apps

Thirty apps. One sign-in. One book.

Every team gets its own app, and every app reads and writes the same loan. Pick a team to see what it opens.

AI is a layer, not an app: the underwriter, credit memo, collections copilot and customer assistant sit inside origination, collections and CRM.

What's different

Five decisions that shape everything else.

01

Journeys are configuration, not code

One lender wants DigiLocker, another insists on CKYC, a third accepts a document upload. One wants video KYC before sanction, another after. In most platforms each of those is a release.

In MODNAR a journey is a versioned document attached to a lender's product, drawn as a flow: drag a step past the sanction diamond to run it later, insert one on an arrow, publish. The next application runs the new flow, and applications already in progress keep the version they started on. The borrower journey and the LOS stage tracker render from the same definition.

02

AI in the underwriting seat

Not a chatbot in the corner. The credit memo is assembled from the bureau report, the bank statement analysis and the KYC record: the same evidence a credit officer would read, in the document they would have spent forty minutes writing.

The recommendation comes with the factors it weighed and the ones that gave it pause, so an underwriter can disagree with the reasoning rather than argue with a score. Underwriting can run manually, on rules, or assisted by a model you choose. In the prototype the memo is drawn from demo data.

03

Multi-tenant from the first line

Not a single-lender product to be made multi-tenant later. Every record carries its tenant, and each lender gets its own branded journey, its own products, its own credit policy and its own users, operated from one platform.

The design isolates lenders with row-level security on the tenant in the database, rather than by developer discipline. Today's browser prototype shows this on the tenant screen; enforcement on the server arrives with the server-side core.

04

The rules engine is yours

The decision policy is the secret sauce of any lender, and it should never sit inside a vendor's release cycle. In MODNAR the BRE is configuration: go and no-go boundary conditions, refer rules, segments that shape the offer, and the models behind them.

Rules today, a scorecard as challenger on a slice of traffic, a PD model scoring in shadow until it earns the seat. A simulator shows what any change does before it is published, every version can be rolled back, and each decision records the version it ran on.

05

Every integration is visible

Bureau, PAN, DigiLocker, account aggregator, penny-drop, e-sign, mandate and payout. Each call is logged against the application that triggered it, with the request, the response, the status and the latency.

Open any application and the whole vendor conversation is there in order, including the retries and the calls that failed. The same log answers the operations question and the finance question: what happened, and what it cost. In the prototype these calls go to sandbox stubs.
One front door

A control panel, not a bookmark folder.

One sign-in. Each person sees the apps their role opens and nothing else. Users, roles and permissions are managed in one place and enforced in every app, not repeated per module.

Onboard a lender

New lender in an afternoon

Identity, RBI registration, grievance officer, product terms, a journey template and a brand colour. A nine-point go-live checklist across legal, compliance, product, engineering, finance and ops. Sandbox first; live means live on the borrower's offer listing.

ChecklistSandboxGo-live
Policies & SOPs

The policy is the configuration

Credit policy, pricing, KYC, fair practices, outsourcing and litigation. Where a policy is live configuration it links into the app that enforces it, so the document and the rules cannot drift apart. Review calendar, versions and owners.

24 documentsReview calendarVersions
Branding & admin

Your name on it

Palette, tenant name and mark applied to every app and the borrower journey in one save. Users and roles, banks, configuration, tenants and the audit trail live in one admin console, and only there.

8 palettesCentral accessAudit
Product explorer

49 products. Zero code.

From personal loans and gold to leases and lines of credit, each product carries its own screens, checks and repayment shape. Open one to see its journey, then run it in the live demo.

Runs end to end in the demo Own journey and checks Not typical for an NBFC (noted) Not allowed for NBFCs
Try it

Decide in the open. Plan to the rupee.

Move the sliders. On the left, a small rule set decides the file with a reason for every outcome. On the right, the schedule re-plans itself.

Rules engine

Illustrative rules. In MODNAR you write your own, version them and publish with maker-checker.

    Approve

    Repayment engine

    The same maths Credit Studio runs, simplified: monthly rest, no fees.

    PrincipalInterest
    First instalment—
    Total interest—
    Total repaid—
    Co-lending

    Two lenders. Three books. Zero rework.

    Each co-lent loan keeps its own book for the borrower, the partner and the originator. Every receipt is split by the arrangement as it arrives.

    • ✓Arrangements with blended-rate or originator-spread pricing.
    • ✓Joint disbursal with partner approval, settlements and import of live co-lent loans.
    • →Next: back-to-back arrangements, the partner console and escrow reconciliation.
    The demo

    Twelve minutes, end to end. Then the rest of the business.

    Every external service is a sandbox stub for now, and the gateway is built so a live provider is a configuration change, not a rewrite. Everything else you can run yourself: apply as a borrower, then open the LOS and find your application waiting.

    1. 01
      Four lenders, one platform

      Arka, Vaishnavi, Sahaj and Nirvaha each run their own journey on the same core. Pick one and the steps change.

    2. 02
      Apply from a phone

      Mobile, OTP, PAN, date of birth and PIN code. The name prefills itself from the PAN record.

    3. 03
      Bureau, decision, offers

      Four eligible lenders, four different offers on the same applicant. Move the amount and tenure and watch the EMI follow.

    4. 04
      Open the LOS: it is already there

      The application exists, every field filled in, timestamped and attributed. Nothing was re-keyed.

    5. 05
      Read the integration timeline

      Every vendor call with its payload and latency. Force the bureau to time out and watch the retry and the fallback to manual review.

    6. 06
      Generate a credit memo

      Written from that applicant's bureau, bank and KYC evidence.

    7. 07
      Approve, sanction, disburse, book

      Sanction letter, payout with a UTR, the loan in the LMS with its schedule, and the balanced GL entry behind it.

    8. 08
      Reconfigure a journey, live

      On the flow canvas, drag video KYC past the sanction diamond, swap DigiLocker for CKYC, publish and run it again. No deploy.

    9. 08b
      Change the credit policy, live

      Raise the score floor in the BRE, publish v4, run the refer persona: it now declines, with the reason. Roll back to v3. Nothing was deployed.

    10. 09
      Collections on a real book

      Two hundred loans with a realistic DPD spread, bucketed, allocated and prioritised. Post a receipt and watch the case cure and the ledger move.

    11. 10
      A complaint, escalated

      Log it on the support desk, breach the L1 clock, escalate to the grievance officer, and find it in the compliance register with the RBI 30-day countdown.

    12. 11
      The rest of the business, on the same book

      A ₹6.5 lakh vendor request routed by the approval matrix to a PO and a matched invoice; payroll posted to the GL; a marketing segment that refuses anyone without consent.

    13. 12
      “Delete my data”

      Log the request, watch the scan find the person across every app, see marketing consent withdrawn automatically, loan and KYC records held with the legal basis stated, and the DPO's one-click decision.

    14. 13
      Onboard a lender

      Create it on the control panel, tick the checklist, go live, then apply as a borrower to see it on the offer listing, ranked by APR like everyone else.

    Film

    See it move.

    The 80-second product film, cut from the real prototype. Or play the short explainer, which is built into this page and narrates itself.

    Straight talk

    What you can touch today.

    MODNAR today is a working, clickable prototype that design partners use to walk through real lending operations. It runs in the browser, with no production backend yet, so here is exactly what that means.

    12journeys you can run start to finish
    49products with their own application screens
    30apps on one sign-in
    0live bureau, KYC or payment connections yet

    Built and clickable

    • Personal loan from application to closure, across every app
    • Rules engine, underwriting modes, Credit Studio schedules
    • Collections, settlement, write-off and legal
    • Double-entry ledger, month-end close, ECL, reconciliation
    • Joint-disbursal co-lending and loan migration

    Simulated for demos

    • Credit bureau, CKYC and DigiLocker responses
    • e-sign, e-mandate, payouts and SMS or WhatsApp
    • Data is stored in your browser, not on a server
    • Products other than personal loan use personal-loan pricing for offers

    Next on the line

    • Server-side core, real integrations and audit trail
    • Revolving limits for lines and cards; lease engines
    • Back-to-back co-lending and the partner console
    • Borrower self-service after disbursal
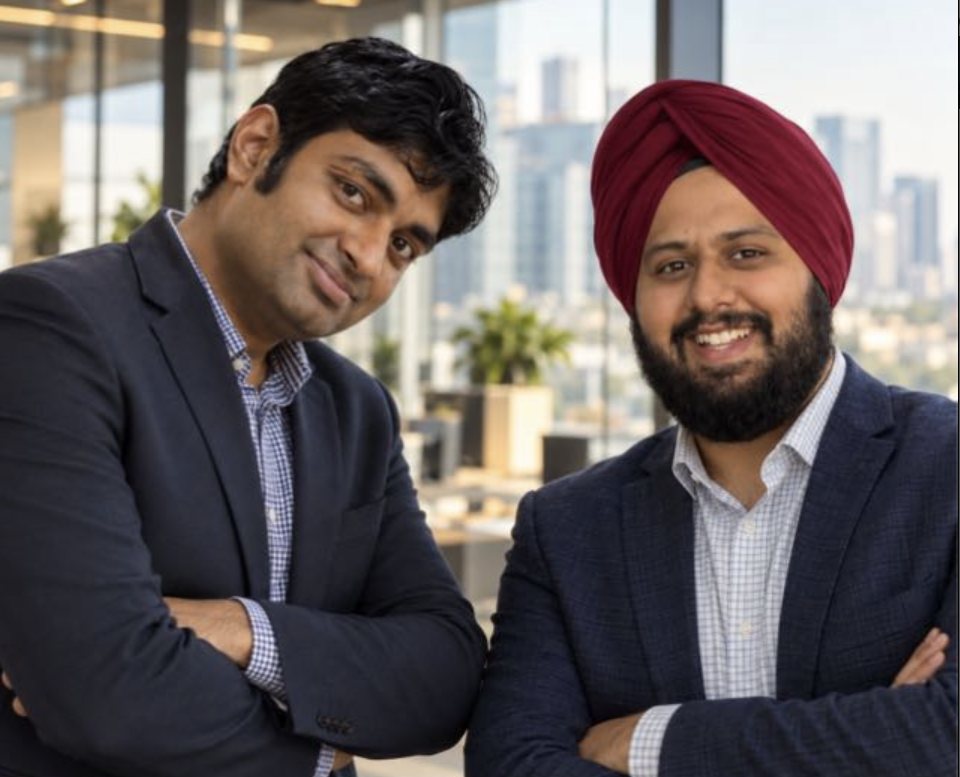
    Rajat Garg and Harnoor Singh, the founders of MODNAR, standing together in an office.
    Founders

    Who we are.

    MODNAR is built by Rajat Garg and Harnoor Singh. It started from a simple observation: an Indian NBFC runs one loan through half a dozen systems that don't talk to each other, and reconciles them by hand. MODNAR puts that loan on one line.

    Rajat GargCo-founder
    Harnoor SinghCo-founder

    Lend faster. Service smarter. Collect with control.

    Walk through any of the 49 product journeys in the live demo, or sign in to open the control panel.

    Design partners. Built to run a real book, starting with yours. The fastest way to judge MODNAR is to put one of your own products into it and push a real application through, end to end. That takes an afternoon, and you keep whatever we configure.